

Edit 14/07: No, it’s not at 5 times. The double discount calculated included an error. it is not available at 5 times earnings but 7.7 times earnings or approx 8 times earnings.
The market is changing, my articles are changing. The opportunities are more clear.
They don’t need very long articles.
Tencent is the company behind Wechat in China. This includes WechatPay and many services.
I never claim to be a China expert. I am a numbers guys and big picture thinker.
The number and big picture are clear: This company is a monster.
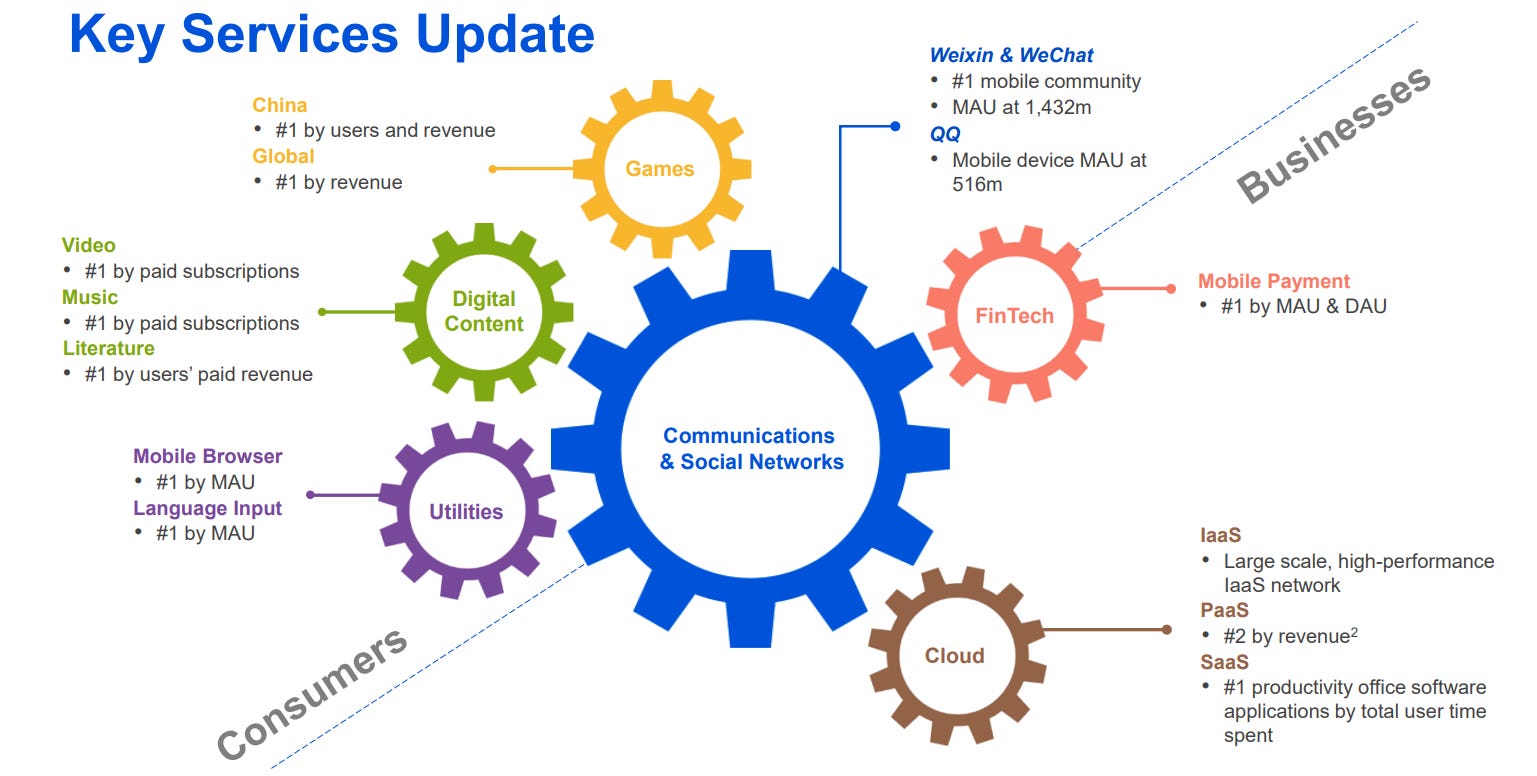
Fintech: 1st in China and the world by active users.
Social networks: 1st in China by number of users.
Games: 1st in China by users and revenue, and globaly by revenue.
Video, Music: first by paid subscribers
Cloud: Here the company is not first but it remains a large player in a key growing industry.
You can see an overview of Tencent positioning in the following slide from the investor presentation.
Sometimes, you feel that a company is too big to be analysed in details. This is definitely the case with Alphabet and Tencent.
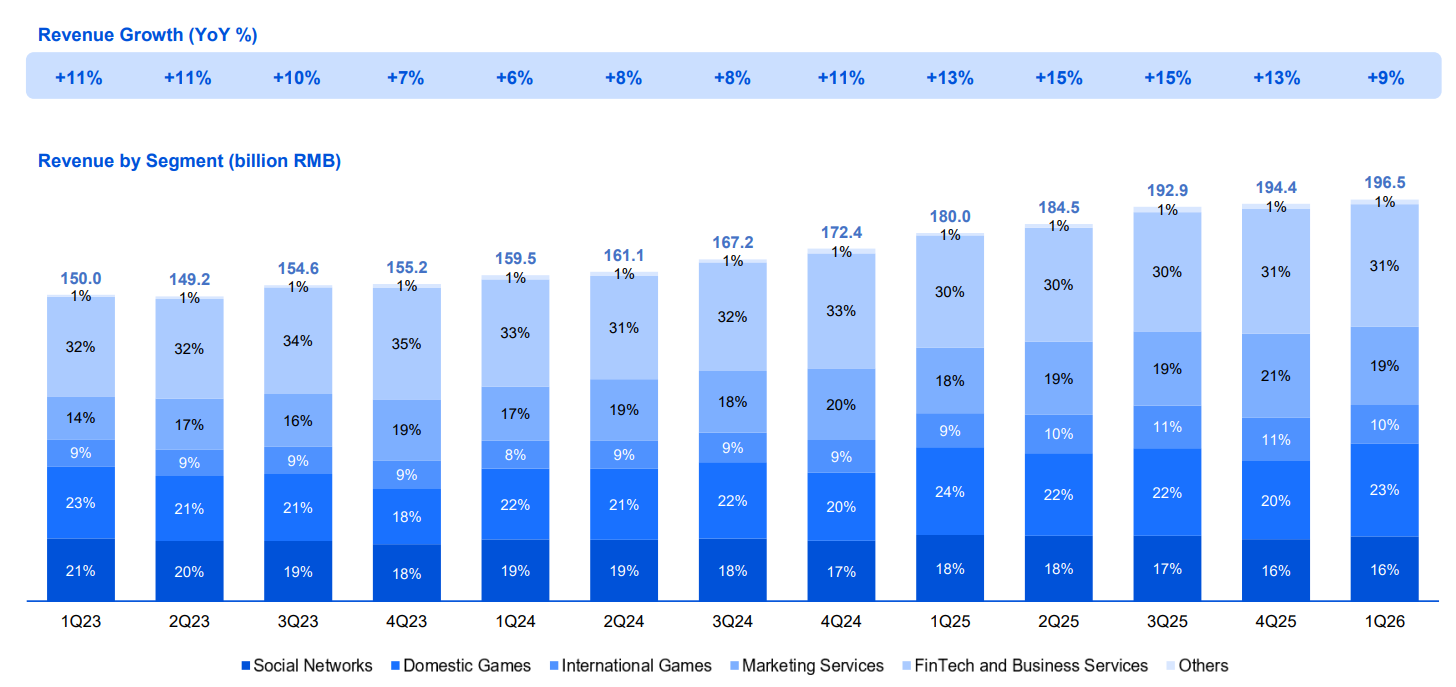
The revenue growth year on year is a solid 10-12% on average.
Social networks are about 16% of revenues as of Q1, gaming 33%, marketing services 19%, Fintech and business services 31%.
The company is powering the Chinese online communications, and being invested in it is investing in the Chinese online ecosystem. It will provide services and collect revenues from the long term growth drivers of the Chinese online economy. And of course from the AI economy in China and abroad.
The installed user base, the network effects and the AI engine ensure continued success in this sector.
I expect China to lead on AI due to higher innovation rate and lower cost of chips and eventually memory too in a few years.
Tencent is investing in AI heavily, with its own cloud operations and LLMs.
I always believed that AI in itself is not going to be a moat, but AI applications and applications to users and data at scale will be a moat. Tencent has everything to be a key player in AI, and workbuddy for example can generate extra revenue, even globally. The key advantages of Tencent AI will be the automation of workloads within the Tencent ecosystems, which is facing customers daily.
The best way to understand where Tencent is is through the annual report introduction:
We sustained healthy growth rates in 2025, as AI capabilities improved our ad targeting and supported more engagement with our games, and as our cloud business delivered improving revenue growth and profit at scale. Our highly resilient and cash-generative core businesses provide us with the resources to fund our increasing investments in AI, including recruiting top-tier AI talent and upgrading our AI infrastructure. The increasing intelligence of our HY 3.0 large language model, and the utility of our AI products such as Yuanbao, WorkBuddy, and QClaw, are encouraging early signs that these investments will unlock new opportunities. People enjoy consuming and being entertained, and derive satisfaction from creating and being productive, and it is Tencent’s privilege to provide AI services that can enhance our users’ capabilities across these dimensions.
Like Meta, AI is improving the core business ad targeting and engagement. The cloud business is growing. The company is in an AI investment phase. It will roll out AI within wechat and it will increase costs, while making the service even better, soon becoming a real life personal assistant of sorts.
Goldman Sachs has developed a bottom-up estimation framework that, by assessing the daily average token consumption of WeChat’s AI agents, estimates that if fully rolled out, the incremental inference costs would amount to roughly 5% to 17% of Tencent’s forecasted adjusted operating profit for the fourth quarter of 2026.
What is interesting is that the capital expenditures did not grow too much like the hyperscalers in 2025:
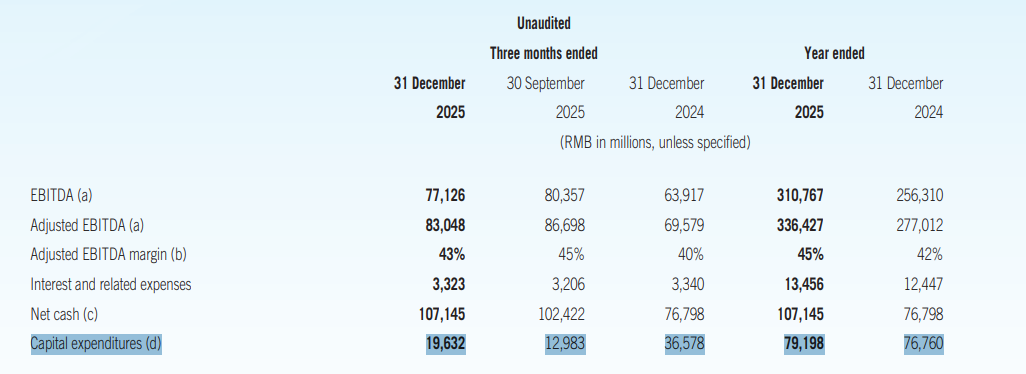
In Q1, Capex was up 16%.
Investment portfolio:
Tencent maintains a large investment portfolio compassing leading tech companies worldwide, and earns good returns on it historically:
As at 31 December 2025, our investment portfolio amounted to approximately RMB957,219 million or $141.25 billion USD — or 26% of the market capitalisation as of July 12.
We can see PDD, Sea limited, Spotify, Kuaishou (content platform), Reddit, etc, and many startups in the portfolio;
How about buying all of this at a crazy discount? Is it worth it? Searching for the cheapest EM stocks is what I do at the emerging value newsletter.