

This is about a company I found when I did the UK small caps A-Z, with a market cap of 95 million GBP
It trades at a PE ratio of 3.6, is growing and is set to pay a 10% dividend at current prices.
Business
The company works in emerging and frontier markets. It borrows mostly to local institutions then issues micro credit to customers.
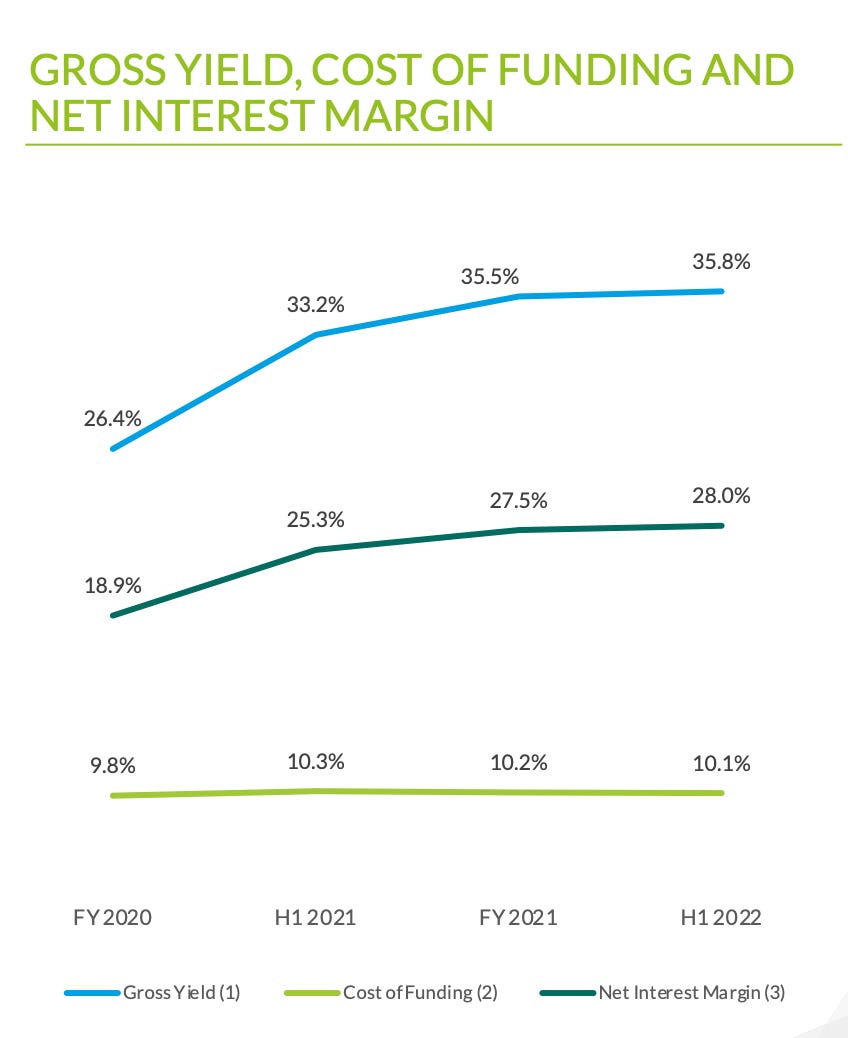
The returns are enormous:
The main countries are Pakistan, The Philippines, Nigeria, Ghana, Tanzania, Sri Lanka etc.
India was a big part of the business but; it is now 12.8% of the group loans outstanding and is voluntarily winding down for now. This has an impact on the group combined growth rate now. More on the risk section. Here is the latest on potentially restarting growth in India.
So we would hope that based on that, once we've seen that's really taking place in action, that we may be able to start rebuilding the business (in India) once it's fully stabilised and that's we expect to see take place throughout the remaining part of this year and probably also throughout the bulk of next year, I would say. Depends a little bit how quickly it will go. Here, I would say. Depends a little bit how quickly it will go. And then, we'll make our decisions what's further investments the group will make in our Indian operations.
Strategy & Management
Here is an overview.
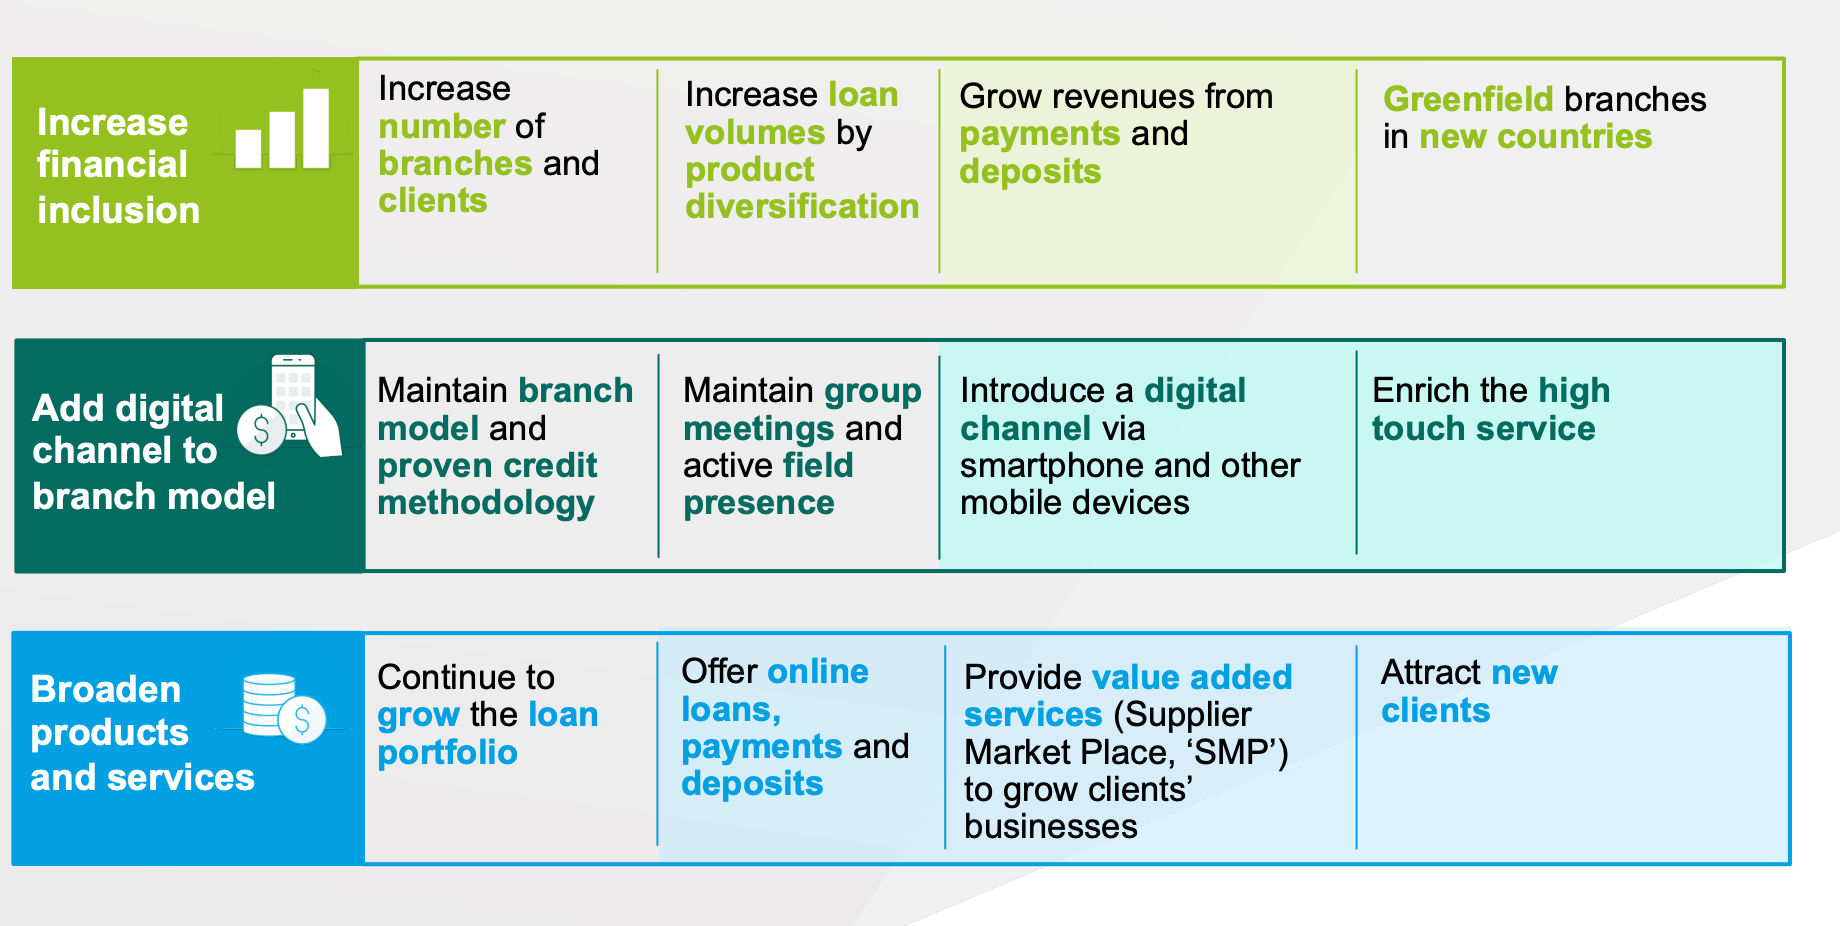
The company grows with the opening of physical branches where it partners with local companies and agents to find and service customers.
-digitalisation with the development of apps (done by Temenos AG) to serve customer easier, faster, and hopefully bring more growth. “the new channel by which we will offer full financial services experience to our clients.” An app is being introduced in Ghana.
-On digitalisation, they are also building “a supplier marketplace platform. It's a digital platform which would allow clients to grow their business. They would not have to close their shop to do their logistics and buying. They could get more attractive prices because of bundling the volumes, and the stock will be delivered at their doorstep.”
I think its pretty genius since they have the clients connections and trust already, and most of their clients have small shops. The margins would not be that huge but it would be beneficiary.
Overall the business and strategy are rated excellent by me.
The company is founder led. The founder just resigned as CEO but will stay on the board. Interests seem aligned.
Market
The company has 2.4 million customers. The market for undeserved credit and financial services in enormous, hundreds of millions of people.
Valuation:
H1 2022 net profit of 13 million or 26 annualised. Market cap is 93 million. The company did solid growth and profits pre covid. Nothing more to add. The stonk is a bargain.
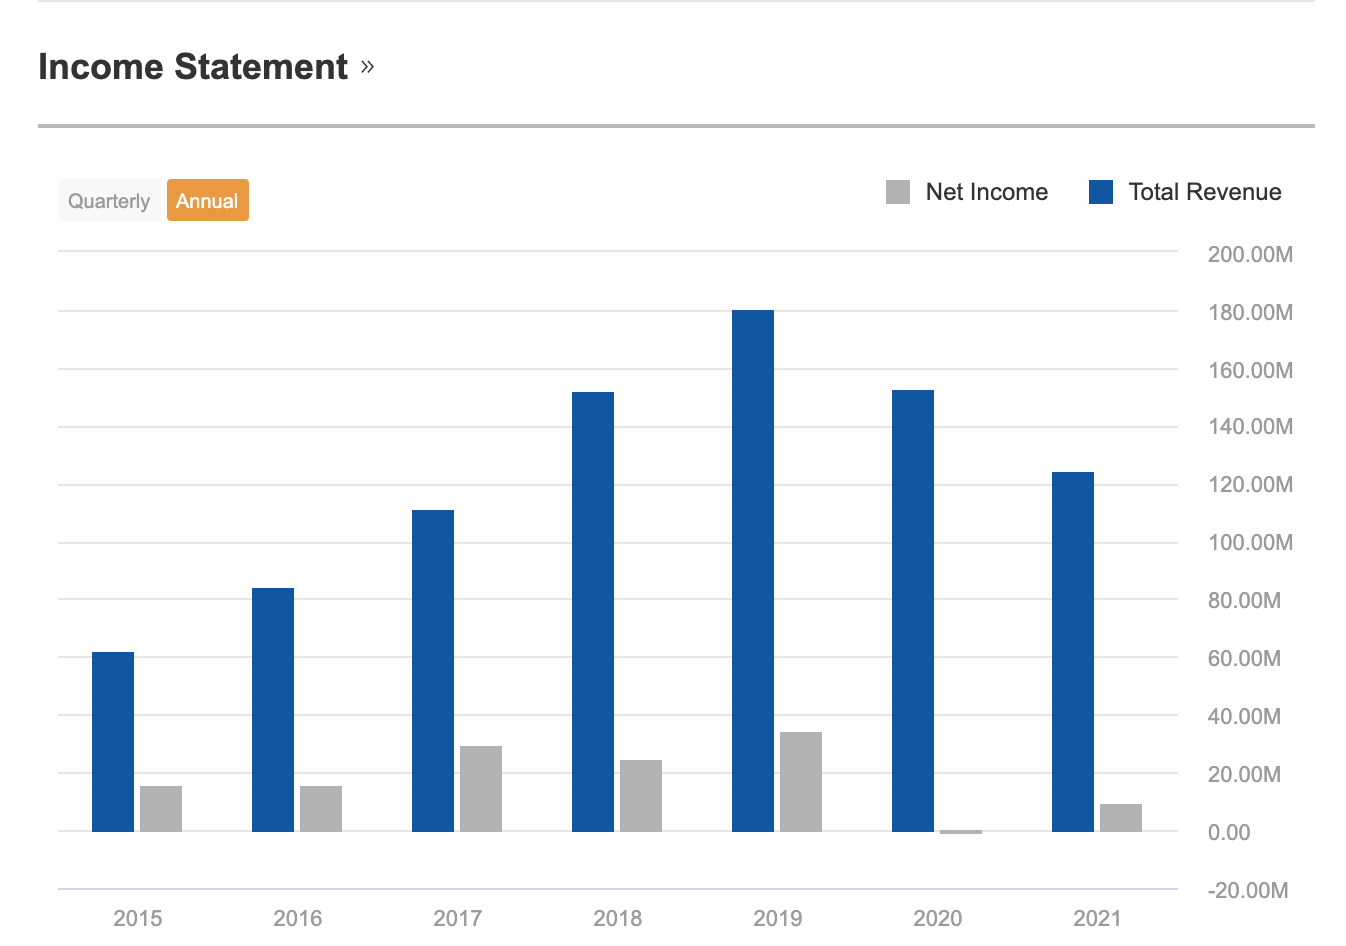
P/B is about 1, so the company earns a good return on it’s book.
The company plans to pay 30% of net income as dividend.
Opportunities:
-Return to growth in India
-Marketplace app and other services.
-General organic growth and growing dividend.
Risks:
there are quite a few in this type of business:
-Currency depreciation in a market reduces returns in USD and can even give a loss in the net interest margin is lower than local inflation. These situations however get normalised with higher margins on new loans. The company actively uses derivatives to manage currency risk. Pakistan, Ghana, Sri Lanka had some troubles recently. However, the company manages to pull through.
-Regulation problems in a market: in India, the company felt that regulation was not supportive enough by caping interest rates, putting moratoriums on repayments, and the subsidiary ended up with a lot of losses due to covid restrictions. Therefore the company is not originating new loans in India for the time being to protect it’s margins. This is hurting growth and the company is now also reporting on growth ex India.
-Large economic crisis that makes that loans are not repaid for a long time. This happened with India and covid lockdowns hurting small businesses and profitability. The company had a minor loss in 2020, and earned less (8 million) in 2021. However I think that this crisis was above a normal emerging market normal crisis due to people movement restrictions. A normal crisis with currency depreciation would hurt profitability but not as much due to the currency risk management.
-Leverage: This risk is well managed because the company borrows in local currencies with local banks before offering the loans. Most are at subsidiary level so the parent listed company is not at risk. The annual report states: “Also, the total outstanding debt at the holding level (ASA International Holding and ASAI International NV combined) is USD 70 million which is part of the USD 314 million consolidated debt for the Group. Most of the covenants under the USD 70 million loan agreements are based on consolidated Group results.”. The company makes nearly 50 million in profit before taxes in a normal year. However, it would be good to reduce the holding company level outstanding debt. The company also has “unrestricted cash” to the tone of 91 million USD in H1. I am not sure what that means, but it looks like it would cover the holding company level debt.
The annual report describes the risks better, all funding in USD is swapped to local currency.
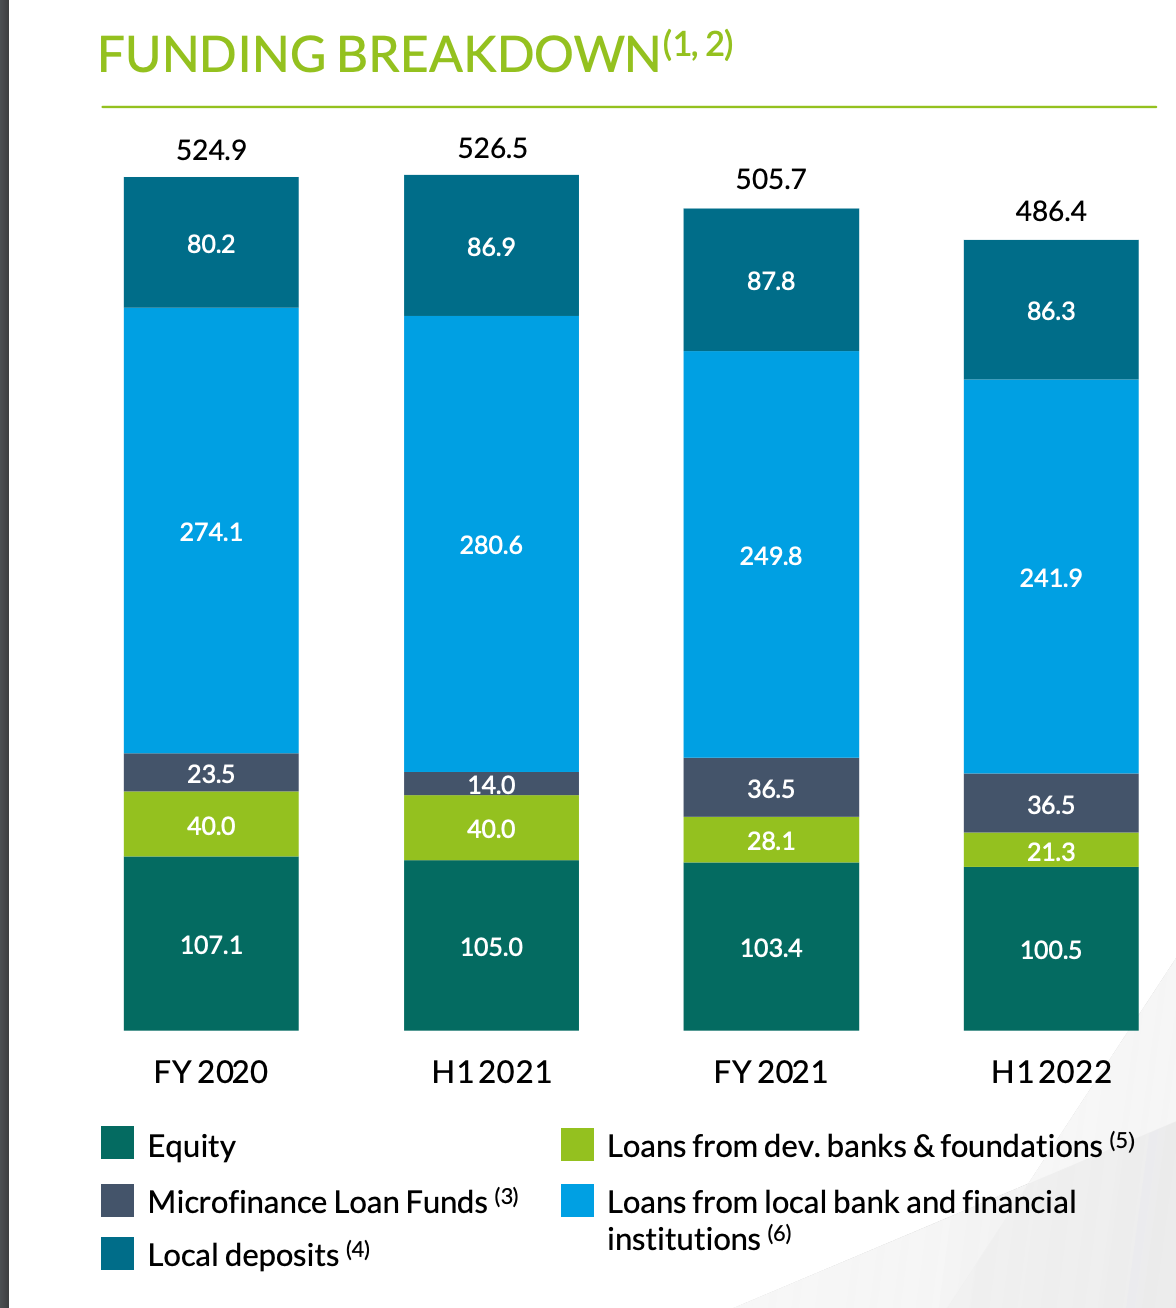
India winding down reduced the overall loans outstanding.
Conclusion
There is a lot of value and growth in this business.
It’s a kind of a black box on the risk side for me. A black box that makes sense from a business perspective, but requires a lot of due diligence to understand all the financial leverage. I like that the loans are mostly in local currency.
I do the most prudent thing in this situation, which is own a 1% sized position and maintain it while extracting value from the dividend (returning in 2023), until I feel that I understand the financial leverage enough to add significantly to the position (maybe never). I want to see the adjacent services start to contribute to the bottom line as well. I could make small reinforcements up to 2% without risking the portfolio.
Note: this is not financial advice, but my opinion on the company. Anyone should do their own due diligence to confirm a company thesis presented and form their independent opinion.
If you like the ideas I send please provide some feedback below! Thanks!!
Getting heart palpitations just reading about the company. Lol. But lending in frontier markets can be profitable. Have heard of pawn shops in Vietnam making 50% net interest margins, for example.