

Value sits untouched in deep corners of the markets while others sectors have the biggest valuations ever. Make no mistake, this is now that people are signing for their ruins again (after 2021) when buying unproven growth stocks at nosebleed valuations. 1 out of 10 will maybe give a long term good return, the rest will follow the road of the weed stocks, the AOL and America Online stocks or at best the Cisco stock returns from 1999. I have no idea which one will be the winner, and 99.9% of non genius growth investors also have no idea.
In other corners of the market, your Free cash flow yields are enough to produce excellent return without market reratings.
The company is a European food company. These products have the particularity of resisting all crises and having the power to raise prices. It is also a company that has done three important acquisitions in the past years and grew revenues and cash flow consequently. It has three more in the pipeline, and is good at integrating them. A risk of dilution to fund a large one negates the picture of a reasonable share price multiplication ahead. A risk well compensated in my mind, due to the undervaluation.
All figures in Euros.
Here is Newlat foods, trading in Italy. The company is family owned and grows by acquisition with huge ambitions.


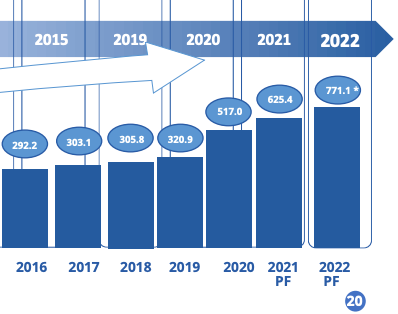
They have made recent acquisitions (Centrale del Latte d'Italia 2019, Symington's 2021 and recently EM Foods, 2022).
Thanks to this, revenues have more than doubled in recent years, as well as the generation of profits, which has grown a little less (inflation and costs).
Focused on acquisitions, the company does not pay a dividend.
At the level of integrating, the company is intelligent and generates synergies such as the cross-selling of products from one country to another, the use of factories to rationalize production or increase the rate of utilisation. The acquisition of the pot noodles in England is a great success as they are selling them in Italy and Germany.
In terms of margin, it's not as high as an AB inbev or Coca Cola. These are mostly pasta, milk, noodles, products with less brand power. Over the last quarter, where the company was able to recover part of the margins lost by inflation, adjusted free cash flow was 7.2 million on sales of 207 million, or 3.5%. Not very high but stable over time. The profit was 6.4 million.
As the capitalization is 263 million, the annual FCF would therefore be 29 million, we have a yield of 11% spot. The company expects 30 million this year.
It should be noted that the latest acquisition, EM Foods, is not profitable because it is in startup and innovation mode, and should bring additional profits from 2023.
Growth strategy
The company has a favorable situation with 300 million in cash and is preparing huge acquisitions to reach the billion and probably two billion billings in the long term.
By using these 300 million cash to buy 20 million FCF, it could therefore earn 50 million FCF / 263 million Capitalization, or 19% return, it is very inexpensive.
The company is currently in active talks regarding 3 acquisitions;
Two of reasonable size and one that makes a billion turnover.
One risk would be a capital issue to pay for the big acquisition target that is making a billion in sales. For that it will have to go into more debt. Newlat could take a maximum of 500 million debts maybe, or pay 0.5 times the sales. Newlat could also buy the company only in part, like 60% or 51% for example.
In June 2023, Newlat issued 8.8% new shares to funds to finance acquisitions, for 20 million. But it previously owned 11.17% of the capital following share buybacks. The operation is therefore neutral for the moment.
However, the new company would surely be revalued higher by the market thereafter due to the change in size by exceeding one billion in sales, even after a dilution.
Conclusion
We have a P/FCF of 9 and potentially 5 after acquisitions using only cash.
So we have a cheap, ambitious and non-cyclical business, but one that risks partially diluting shareholders. For me, that's enough to get a position.
I am planning for a double (no acquisition) or a triple or more (acquisitions with or without dilution). Spanish fund truevalue.es also shares this view. This is led by a great analyst, but in my opinion his other ideas are a bit more risky than what I search (IT services, subprime finance). However on Newlat, an ultra defensive company, we agree fully.
Note: this is not financial advice, but my opinion on the company. Anyone should do their own due diligence to confirm a company thesis presented and form their independent opinion.